Monday, July 20, 2015

Transport Econ 15, On having 2 cars or more

Heavy traffic in many areas of Metro Manila is a daily reality. Here for instance, Roxas Blvd. in Pasay near the Baclaran Church. I took this one Saturday morning last month, I was on a pedestrian  overpass.

Because almost everyone experiences heavy traffic, then almost everyone has a proposed solution how to solve it, which is not really a bad thing. What makes things bad is when  some people would propose solutions that will impose more restrictions on the rest of society. Like (a) prohibiting people from driving and using their own cars one day a week (aka plate "number coding" ban). Or (b) prohibiting certain modes of transportation and ride sharing (air-con vans, some provincial buses).

One solution proposed by some people and represented by these old, abandoned cars, is that we "bury our irrational desire for more private vehicles, have more space for mass public transportation," and "moderate our greed for cars."

People respond to incentives and disincentives. When government imposed that we cannot drive/use our car, our own private property, one day a week, some people who can afford started buying a second car, or at least a motorcycle.

Again, if you live in UP Village, or Filinvest QC, and you are going to Makati CBD or Ortigas , if you take the public transpo, it's four rides one way: (a) tricycle from house to Commonwealth ave or Philcoa, (b) jeep to MRT station, (c) MRT ride, then (d) jeep or van to destination. Coming home, the same four rides, or eight rides a day. It may be cool if one is wearing shorts and rubber shoes, but if wearing barong or corporate attire, carrying a laptop and other important docs, or big cash, would you dare taking those 8 rides a day? Most likely not. 

So people endure driving their cars even in heavy traffic. But other people should not blame the hapless middle class motorists who refuse to be harassed with 8 rides a day. That's unfair. Those who wish to endure it, fine. Those who don't want to, we should not call them "moderate their greed for cars," and "greed" is defined as having two or more cars. 

When the MMDA and LGUs prohibited people from driving our own cars one day a week, that is already wrong. But people comply with this ruling, and some buy a 2nd car for coding day of the main car, or when the other car is in a repair shop. But why call them "greedy" for having a second car?

Not that I own two or more cars, I own only one, an old one. But I will debate people who say that owning 2 or 3 cars are greedy. What do they know of the circumstances why some households have opted that way, an expensive way?

If parents also have to bring the kids to school before going to work, that makes 4-5 rides one way, or 8-10 rides a day or more. This is not nice nor cool. Thus people have to drive their cars. Then there are households with special needs, like bringing a sickly child or grandpa/grandma to regular medical check ups, then the couple must drive to work too, they will need 2 cars at least. Maski luma or bulok basta may air-con and functioning. To condemn them of being "greedy with cars" despite their special condition is wrong and irresponsible.

One solution to reduce traffic in Metro Manila and other major cities in the country is to allow various forms of ride-sharing and car pooling, government agencies like LTFRB, MMDA and LGUs should step back from more prohibitions, more regulations, more bureaucratism. People simply want to take one ride from house to work whenever possible. If air-con vans, if Uber system can provide this, why over-regulate and prohibit them?

On the earlier proposal by environmentalist lawyer billed as "Akin ang Tondo, Sa Iyo Ang Cavite" -- dividing roads in Metro Manila, 1/2 or 2/3 to cars and buses, 1/2 or 1/3 to bicycles and pedestrians. 

For me, this is a lousy proposal. You do not mix cars with bicycles and even pedestrians in Edsa, a very congested and major road. Not everyone is careful, whether the cyclist or motorist or pedestrian. If one or more people die in an accident in Edsa, say a novice bicyclist who suddenly swerves to the lane for cars, or a novice or sleepy or drunk motorist who swerves to the bicycle lane, who is to blame? The bicyclist, the motorist, the government, or Tony Oposa and his supporters?

Do NOT mix them in Edsa, it is a stupid idea. Bicycles and pedestrians should have their own lanes, elevated from the main road, so that cars and buses cannot easily swerve onto them.
-------------

See also: 
Transport Econ 11: On Fare-Contracting Taxi Drivers, December 13, 2013
Transport Econ 12: Bus Rapid Transit (BRT) and Tricycles, April 21, 2014 

Transport Econ 13: On Prohibiting S. Luzon Provincial Buses to Enter M.Manila, August 30, 2014 

Transport Econ 14: On the MRT and LRT Fare Hike, January 06, 2015

Sunday, July 19, 2015

Asian free market websites, Part 4

(I originally posted this early morning July 12. My updates for today, below)

How popular are the free market think tanks and institutes in Asia, at least online?

I checked alexa.com four years ago to answer that question. Today, out of curiosity, I checked again alexa.com and here is what I discovered. Shown are their global ranking -- out of several hundred million sites and blogs in the planet.

1. Korea Economic Research Institute (KERI), Seoul, headed by Dr. Tae-shin Kwon, represented by Dr. Choi Byung Il in various EFN Asia conferences.
2. Unirule Institute of Economics, Beijing, headed by Dr. Mao Yushi; often represented by Dr. Feng Xingyuan in various EFN Asia conferences.
3. Policy Research Institute of Market Economy (PRIME) Institute, Islamabad, headed by Ali Salman
4. Freedom Institute , Jakarta, headed by Dr. Luthfi Assyaukanie, among others.
5. Institute for Democracy and Economic Affairs (IDEAS), headed by Wan Saiful Wan Jan.
6. Suara Kebebasan, Jakarta. Not exactly a think tank but a website for freedom, headed by Adinda Tenriangke Muchtar.
7. Samriddhi The Prosperity Foundation, Kathmandu, headed by Robin Sitoula.
8. Minimal Government Thinkers, Inc./Funwithgovernment blog, Manila, headed by yours truly.
9. Liberty Institute, Delhi, headed by Barun Mitra.

The numbers in green are the increase in global rank over the past three months. In red are decrease in global rank over the same period. Notice the huge jump of these think tanks below in a short period of time.


10. Doimoi.org, Hanoi, is a think tank that translates some important classical liberal books and literatures into Vietnamese, headed by Cong Minh Nguyen.
11. In defence of liberty is another project of Liberty Institute, Delhi, headed by Barun Mitra.
12. Japanese for Tax Reforms (JTR), Tokyo, headed by Masaru Uchiyama or Mr. You.
13. Center for Civil Society (CCS) Delhi, headed by Dr. Parth Shah.
14. Foundation for Economic Freedom (FEF), Manila, headed by Calixto "Toti" Chikiamco.
15. Alternate Solutions (AS) Institute, Lahore, headed by Dr. Khalil Ahmad.
16. Lion Rock Institute (LRI), Hong Kong, headed by Bill Stacey.
17. Akademi Merdeka, Jakarta, is another project I think, of Freedom Institute.

Friedrich Naumann Foundation for Freedom (FNF) is not a think tank, it is a German political foundation, that supports many Asian free market think tanks, mainly through the Economic Freedom Network (EFN) Asia, based in Bangkok. I just added here the website of FNF Philippine Office, headed by Jules Maaten.

Compared to US free market think tanks, institutes and foundations -- like Cato, ATR, Atlas, Heritage, AEI, Reason, etc. -- we from Asia have a lot more to learn and expand.

UPDATE, July 19:

I am expanding the list of Asian free market think tanks and institutes from 17 to 23 and checked their global ranking via alexa.com today. The six institutes added are:

1. IPencil Economic Research Institute, Beijing,
2. India Institute, Delhi,
3. Shanghai Institute of Finance and Law (SIFL), Shanghai, headed by Fu Weigang,
4. Open Radio for North Korea, Seoul,
5. Asia Center for Enterprise (ACE), Delhi, headed by Baishali Bomjan,
6. Teach North Korean Refugees, Seoul, headed by Casey Lartigue.

In terms of online popularity, here's the ranking as of today.


1. keri.org, Seoul
2. impencil.org, Beijing
3. unirule.org.cn, Beijing
4. primeinstitute.org, Islamabad
5. indiai.org, Delhi
6. suarakebebasan.org, Jakarta
7. ideas.org.my, Kuala Lumpur
10. samriddhi.org, Kathmandu
11. nkradio.org, Seoul
12. sifl.org.cn, Shanghai
13. acenetwork.asia, Delhi
14. libertyindia.org, Delhi
15. ccsindia.org, Delhi
17. doimoi.org, Hanoi
18. jtr.gr.jp, Tokyo
19. fef.org.ph, Manila
20. lionrockinstitute.org, HK
21. asinstitute.org, Lahore
22. akademimerdeka.org, Jakarta


Will update in the coming days.
-------------

See also: 
Asian free market websites, part 2, April 25, 2011 
Asian free market websites, part 3, May 10, 2011 
EFN Asia 31. Friends in the Asian Free Market Movement, November 07, 2013

Saturday, July 18, 2015

Business 360-27, Public health in Asia

* This is my article for July 2015 issue of the business magazine in Kathmandu, produced monthly by Media 9.

The state of public health in Asia

We often hear complaints and  litanies about how our lives are deteriorating and how our health condition is getting more “critical.” Are there solid basis for these statements aside from the subjective observations and emotional sentiment attached to them?

Let us check some health data and see how valid or invalid those observations are. The Asian Development Bank (ADB) has a good compilation of social and economic data spanning for two decades or more, so  we can see a trend of improvement or deterioration of the social  and  economic lives of Asians. 

Below, mortality or rate of death among the young, infants and children below five years old.

There have been drastic improvements in the health condition  of young Asians. Mortality rate for both infants and under five years old in just 22 years were slashed by half in India and Pakistan, and by one-third in Nepal, Bhutan and Bangladesh. A great achievement.

The same trend of drastic reduction in mortality rate for the young is observed in South East Asian countries. In the case of developed economies like Singapore, S. Korea and Japan, the already low  figures have further gone down.

In the past, tuberculosis (TB) was a major killer infectious disease in many countries in  the developing  world. Drugs and treatment against various bacteria that cause and spread the disease were not so developed, and the system of isolation for infected people and proper hygiene for the rest were also  not well-developed.

Consistent with the trend and  data in the above table, death rates from tuberculosis have also significantly gone down after 22 years, slashed by half in Nepal, Pakistan  and  India. Bhutan made very significant progress here. Sri Lanka has an excellent record, comparable to the developed Asian economies like Singapore and Japan.


The same trend is observed among South East Asian countries. Cambodia showed good improvement but its death rate from this disease remains very high, 3x that of Nepal, India and Vietnam.

So if less people are dying, that means the average life span of Asians as well as other people in the world is rising, right?

The numbers below confirm this. Many countries in South Asia showed significant improvement here, life span rose by an  average of 14 years after 22 years. For the people in South East Asia, the increase in life span has increased by an  average of five years. But in the case of Laos, Cambodia and Myanmar, the harsh dictatorship and even genocide they experienced meant very low life span in the 1970s, 80s up to 1990. Diseases plus political murders have cut short the lives of millions of people there until the 80s.

The three tables and sets of data above have shown  that the pessimistic and emotional view that “our lives are deteriorating, public health is in critical condition” has no basis. Our lives are improving, we are living healthier and longer. And that means we now have longer productive years. Instead of dying at age of late 50s or early 60s, many people now remain productive even in their late 60s or 70s, are able to enjoy the company of their grand children much longer.

While some sectors will give high credit to government investments in public health, they sometimes  fail to notice or mention the role of healthcare competition among private healthcare providers – hospitals, clinics, drugstores, drug manufacturers, physicians, pharmacists, nurses and other health professionals.

Governments in Asia and other parts of the world should recognize the role of healthcare competition among private players and professionals. The goal is longer life span for  the people, few people dying from infectious diseases, and not more government hospitals per se.
----------

See also:

BWorld 11, China's stockmarket and central planning

* This is my article in BusinessWorld Weekender yesterday.

HIGH DEBT, private and public, will always create financial turmoil, today or tomorrow. The ongoing fiscal drama in heavily indebted Greece will continue for many months to come, whether it will stay using the Euro or not. And recently, it was China’s turn with the recent near-crash of its stock markets in Shanghai and Shenzen, and partially affecting the markets in Hong Kong.

Unlike the markets in the US, Japan, UK, Germany and other democratic countries, the case of China will always be internally conflicting. It is a dictatorship that abhors political competition and yet it wants to mimic economies that allow market competition.

HIGH PUBLIC DEBT
Officially, China has a gross public debt/GDP ratio of only 41% in 2014, manageable and just slightly higher than the debt/GDP ratio of Taiwan and South Korea (38% and 36%, respectively). But China has more debt than what it will officially admit.

A report by McKinsey Global Institute recently said that China’s total borrowings (individuals + companies + local and central governments + state enterprises) was 282% of GDP in 2014. This is very high for a non-industrialized economy like China.

There is high-margin lending (borrowed funds for stocks investment), reaching $323 billion last month alone, invested in the stock market by many novice, first-time stock investors numbering in tens of thousands.

STOCK MARKET BUBBLE
From 2010-2014, China’s stock market capitalization/GDP ratio averaged only about 45%. By June 12 this year, it rose to almost 100%, showing a huge asset price bubble in the first half of this year.

In comparison, this ratio is mildly increasing in the US (around 140% in 2014) and Japan (nearly 100% in 2014) from 2011 up to the present. 

Figure 1 (from Bloomberg)


The bubble started last year when government media repeatedly announced that stocks were cheap, with the implicit understanding that the central planning authorities can control prices from falling. Millions of novice and first-time stock investors came in droves, China’s market capitalization tripled and reached $9.8 trillion, according to a Bloomberg report last June 30.

From 2011 to mid-2014, Shanghai’s price-to-earnings (P/E) ratio was only around 12. By late 2014-mid-2015, this rose to 26, more than double in less than one year.

BUBBLE CRASHED
Why did the bubble burst so suddenly? There are several explanations and hypotheses for this.

One is that China is experiencing a GDP growth slowdown of “only” 7% or less, compared to 9-12% per year for the last three decades or more. Two, some government stimulus programs to shield China from various global turmoil have to end. Three, finance also follows the law of gravity: the speed and height of price rise is somehow directly proportional to the speed and depth of price decline.

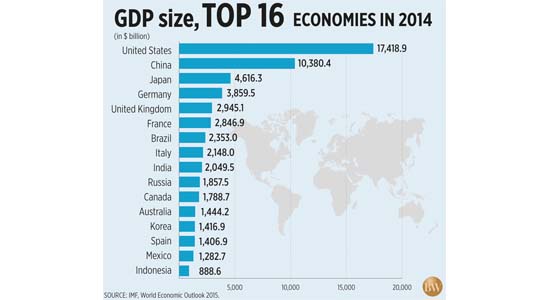
The magnitude of the stock price decline was $3.9 trillion, according to the Bloomberg China Market Cap index. That was equivalent to the GDP size of Germany, larger than the GDP sizes of UK or France or Brazil, and twice the GDP of Russia. 

Figure 2.

The bulk of China stock investors are the more than 90 million individuals who make up about 80% of the market, according to a survey of households.

The stocks crash was worse than the US property crisis in 2008-09, although in terms of global interconnection and contagion, the US financial turmoil last decade had a larger impact. Significant deterioration in the public debt of Greece, Spain, Portugal, Ireland, Cyprus, Italy, etc. occurred in 2009 and 2010, obviously a result of contagion from the US.

Compared to the Greece debt problem, this is much larger. Greece’s GDP size in 2014 was only $238 billion, and its total public debt was about $320 billion.

CENTRAL PLANNING FIGHTS BACK
China’s government responded with several measures. One, the central bank cut interest rates, hoping that more savings from the banks will go to the stocks market. Two, some stock traders and speculators were investigated with threats of prosecution for stock rumor mongering. Three, a number of planned initial public offerings (IPOs) were suspended. Four, outright stop in trading.

From Bloomberg reports:

“At least 1,301 companies have halted trading on mainland Chinese exchanges, locking up $2.6 trillion of shares, or about 40 percent of China’s market capitalization. The China Financial Futures Exchange raised margin requirements for sell orders on CSI 500 index futures, while the central bank will provide “ample liquidity” to the stock market. China Securities Finance Corp. said it will buy more shares of small- and mid-cap companies.” (July 8)

“Official measures to support shares became more extreme during the week as declines deepened. They include a ban on stockholders and executives from selling stakes in listed companies for six months, an order for companies to buy equities and an investigation by the nation’s public security bureau into short-selling.” (July 10)

LESSONS FOR SOUTHEAST ASIA
Emerging economies in the region like the Philippines can draw lessons from this latest episode in regional and global economics.

1 Moral hazards. When a central planning government rallied the public to invest in the market, many investors with little or zero experience in the market came believing they couldn’t lose money since the government is big enough to guarantee returns or bail them out later.

2 Adverse selection. Millions of new novice investors have picked up the wrong timing, at a time when fiscal uncertainty hounds the EU and China was experiencing growth slowdown. Adverse selection often results in adverse results.

3 Debts and uncertainty. As public and private debts become bigger and bigger, the economic uncertainty also becomes bigger. People will never know who can pay back and when, and who will default.

4 Corporate fundamentals. Investors should do hard analyses of the fundamentals of companies whose stocks they are buying, and not just wait for cues and pronouncements from government. It can be a case where as government intervenes more, it creates more panic and price volatility.

5 Central planning and central disappointment. Central planning cannot and will not cure and control everything, including stock price ups and downs, boom and bust. Central planning works mainly to postpone small busts to become huge busts and bursts. Authoritarianism can never be compatible with free markets.

6 Role of government. The state and its various agencies, from local governments to different regulatory agencies to monetary authorities, should focus on ensuring fair market rules rather than guaranteeing outcomes.

Bienvenido S. Oplas, Jr. heads a free market think tank in Manila, Minimal Government Thinkers, Inc., and is also a fellow of South East Asia Network for Development (SEANET), a regional center based in Kuala Lumpur advocating economic freedom in the region.
--------------

See also: 

Friday, July 17, 2015

IPR and Medicines 35, New paper from Geneva Network

Minimal Government Thinkers, Inc. is a partner of two international free market network dealing with property rights protection including intellectual property rights (IPR) -- the Property Rights Alliance (PRA, based in the US) and the Geneva Network (GN, based in UK). PRA is an old, established network and among its important projects is the production of the International Property Rights Index (IPRI) annually. GN is a new network, born only this year and it produces occasional papers and holds some public events/lectures from time to time. PRA is headed by Lorenzo Montanari and GN is headed by Philip Stevens, both are good friends of mine.

GN has produced this week a new paper, 3-pages The TPP, data exclusivity and public spending on medicines. The Trans-Pacific Partnership (TPP) negotiations create a number of conspiracy theories that are, well, unsubstantiated conspiracies. Like if period of regulatory data protection (RDP) aka "data exclusivity" for biologic medicines is increased, then it will increase public spending on new, essential medicines and reduce public access to them and hence, adversely affect public health.

GN Director Philip Stevens showed data that when Canada increased RDP from 0 to 8 years in 2006, it did not result in any rise in pharma expenditures/total health expenditures (THE). Japan also increased RDP from 6 to 8 years in 2007, there was no significant increase in the ratio in the succeeding years.

Phil concluded his paper with this observation,

"There could be many explanations for this result, ranging from changes in procurement policies to increases in the number of medicines that whose patent terms have expired. The evidence presented above, however, suggests that those concerned about access to medicines and the financial sustainability of public healthcare systems should focus their attention on policies other than Regulatory Data Protection for medicines."

Good paper Phil, as usual.
--------------


Thursday, July 16, 2015

AEC 15, ADR Institute discussion on trade and investments

Yesterday afternoon, I attended a round table discussion  on “The Role of Exports and Foreign Direct Investments in Industrial Development” sponsored by the Albert del Rosario (ADR) Institute (formerly Stratbase Research Institute), Tower Club, Philamlife Tower, Makati City.


The convenor and main speaker was Dr. Epictetus Patalinghug (UP College of Business Administration, and a Trustee of ADR Institute). He presented many data about economic  competitiveness in relation to the forthcoming ASEAN economic integration.

Discussants were Dr. Gilbert Llanto (President of the PH Institute for Development Studies/PIDS), Dr. Ramon Clarete (UP School of Economics/UPSE Prof. and former Dean), Mr. Donald Dee (Honorary Chairman, PH Chamber of Commerce and Industry/PCCI), and Atty. Wilfredo Villanueva (Head of Tax and General Counsel, SGV & Co.). 

Below, from left: Atty. Villanueva, Dr. Llanto, Dr. Patalinghug, Dr. Clarete, Mr. Dee.


Atty. Villanueva mentioned in his reaction/discussion that in the ASEAN, the PH has the highest corporate income tax at 30 percent. The average for the other 9 countries are 22 or 23 percent. And socialist Vietnam has only 22 percent, to go down  further to only 20 percent next year.

Other guests and invitees were people from academe, exporters, officials from DFA and Department of Trade Industry (DTI) like Export Marketing Bureau (EMB) Director Senen Perlada. Amb. Cesar Bautista (also a former DTI Secretary) of the Management Association of the Philippines (MAP).


Foundation for Economic Freedom (FEF) President Toti Chikiamco, Employers Confederation of the Philippines (ECOP) President Edgardo Lacson and Mr. Dee.

Officers from at least 4 foreign embassies (UK, Japan, Australia, plus another one or two), etc. Plus ADR Institute staff and two business reporters.

I spoke during the open  forum. I said that to have more trade and investments, what people really want actually is not good governance but less governance. Not good tax administration but less taxation.  That in a free society, all things are allowed except for a few prohibitions -- like no killing, no stealing, no rape, kidnapping, etc. In (totally) unfree society, all things are not allowed except when one gets a government permit. See the experience of many entrepreneurs, yearly they must get and pay for a barangay permit, health and sanitation permit, electrical permit, fire department permit, Mayor's permit, etc. Local governments alone. Then BIR, DTI permits, SSS, DOLE permits, etc. for national government agencies.

I also cited the WB’s Doing Business 2015 Report, exporters in Singapore file only 3 documents, wait for 6 days to export, and pay $460/container on average. In contrast, exporters in the Philippines file 6  documents, wait for 15 days and  pay $755/container. (Photo below from Arpee Manhit)

And I added that capitalism is a good system, it allows free market and free individuals. Now even the Pope is against capitalism, and many people including many academics and facebook users are anti-capitalism, yet they so love fb (and youtube, google, twitter...) all of which are 100 percent products of capitalism.

A friend commented that I was “preaching to the choir”. I replied that it’s not the case. First, I was not a preacher/discussant, just an ordinary participant. Second, there were a number of government officials there from DFA, DTI,. Third, not all academics believe in minimal government, majority are believers of "big but good government", the source of most of their consulting work.


Thanks again to ADR Institute, especially Prof. Dindo Manhit, for that invite. Good to hear the presentations and comments from other participants. Meet old and new friends. All photos above except 2nd to the last and from Arpee) are from the ADR Institute fb page. Thanks Mikee M.
------------

See also:
AEC 11: Trade and Economic Development is Social Development, April 25, 2015 
AEC 12: Workshop on Trade Liberalization at the APF 2015, Kuala Lumpur, April 27, 2015 
AEC 13, SEANET Website, AFAS in Financial Services, June 18, 2015 

AEC 14, SEANET-ABAC Meeting, IDEAS-OBG Partnership, June 24, 2015

Free Trade 36: Taxation, Regulations, Trade and Rule of Law in ASEAN, August 05, 2014
Citizen Watch 2: On Power and Jobs, August 30, 2014

New Think Tank, Albert Del Rosario Institute for Strategic and International Studies, November 24, 2014 

ADR Institute, Part 2, November 26, 2015

Monday, July 13, 2015

Business 360--26, Nepal earthquake and lessons from it

* This is my article for the business magazine in Kathmandu, June 2015 issue.

Earthquakes and economic growth

The people of Nepal are still recovering from the huge destruction of the 7.8 earthquake (EQ) last April 25 plus succeeding tremors that occurred almost daily. Those tremors have killed 8,000+ people and injured thousands more.

Some hard lessons must be learned and relearned from those events. And not only for Nepal but many other developing countries, in particular, other Asian countries in  the “Pacific Ring of Fire.”

One, EQs are part of nature, part of the continuing evolution of our planet’s geography and geology. Thus, mild or strong EQs and volcanic eruptions are as natural as wet-dry or winter-spring-summer-fall seasonal cycle in the planet.  

For instance, as of May 16,  Asia has had (magnitude 1.5 or greater) 70 earthquakes (EQs) in the past 7 days, 223 in the past month, and 1,650  in the past year. (source: http://earthquaketrack.com/v/asia/recent)

That means that about 10 EQs a day occur in Asia alone over the past week and month,  and 4.5 EQs a day over the past year. The magnitude 7.8 EQ with epicenter in Bharatpur last April is the biggest EQ in Asia this year. Below is a review of very strong EQs over the past decade, most of which occurred in Indonesia (ID), Japan and Philippines (PH).

Table 1. Huge earthquakes in Asia over the last 10 years.


The super-strong EQ in in the waters of Indonesia in January 2004 has created huge tidal waves in the Indian Ocean and killed more than 230,000 in 14 countries. The EQ in the waters of Japan in March 2011 also created huge tsunamis and killed nearly 16,000 people and injured several thousands more. 

Below is a list of very strong EQs in Asia that occurred more than a decade past.

Table 2. Huge earthquakes in Asia more than 11 years ago.


Two, strong structures are required especially in countries which are in big, long EQ faults and volcanic belts. Countries and islands in the “Pacific Ring of Fire” where about 80 percent of all earthquakes and volcanic eruptions occur, from north to south America, and from north  to  south east Asia, are particularly more vulnerable.

Three, EQs in mountainous  countries like Nepal can cause more destruction than EQs of same magnitude in flat or valley countries and islands This is because mountainous areas are prone to huge landslides and ice avalanche if those mountains shake  strongly.

Four, more economic growth, higher productivity of the people will allow them to  have more income so they can build or buy stronger houses and  buildings that will  not crack or  collapse even for EQs that are magnitude 7-8 strong.

And five, governments of EQ-prone countries should be strict in monitoring and enforcing strong building qualities but relaxed and non-bureaucratic in imposing property and structural taxes and fees. The purpose is to unburden the owners and builders of those structures of high taxes and fees so they can spend more resources in ensuring the stability and quality of their buildings. 
-------------

See also:


Saturday, July 11, 2015

BWorld 10, Greece crisis, pension and rule of law

* This is my article in BusinessWorld Weekender, July 9.

Greece’s debt crisis and lessons for thePhilippines

AFTER piling more than 300 billion euros of public debt, Greece could not pay some of the maturing obligations. It defaulted paying $1.6 billion to the International Monetary Fund (IMF) last week.

How did Greece and its people dig this deep hole of debt?

By living beyond their means, by overspending each year without exception, for decades. It also did not follow many of the conditions of its lenders, especially on spending cuts and revenue increases, a.k.a. “austerity” measures.

SPICY-G DEBT

Below are the heavily indebted EU economies of the European Union, especially the SPICy-G countries (Spain, Portugal, Ireland, Cyprus, Greece) that have adopted the euro. The United Kingdom is part of the EU but does not adopt the euro and is excluded in this list. Germany is not exactly heavily indebted, but it is the main lender to its highly indebted neighbors, so it is included here for comparison. (See Figure 1)

The turning point for these indebted countries was the housing and properties bubble burst that started in the United States in 2008. By 2009, the contagion affected many EU economies. The SPICy-G countries suffered significant increase in their debt/GDP ratio from 2009-2013. But all of them have somehow stabilized by 2014 by biting the bitter bullet of austerity measures, except Greece.

PENSIONERS AT 26, 51 YEARS OLD

When majority of Greece voters supported the socialist-leaning Syriza Party headed by Alexis Tsipras in January 2015, they also supported Mr. Tsipras’s agenda to fight austerity measures that were stipulated in previous bailout funds.

Among the factors why Greece’s public finance is heavily compromised is their generous retirement and pension system, which required additional public borrowings. In December 2014, Greek Labor Minister Yiannis Vroutsis reported to the parliament, as quoted by news reports:

“In the public sector, 7.91% of pensioners retire between the ages of 26 and 50, 23.64% between 51 and 55, and 43.53% between 56 and 61. In IKA (Social Security Fund), 4.44% of pensioners retire between the ages of 26 and 50, 12.83% retire between 51 and 55, and 58.61% retire between 56 and 61. Meanwhile, in the so-called health funds, 91.6% of people retire before the national retirement age limit.”

So people then can opt for early retirement at age 26 and get monthly pension from the state. Wow. Until 2009, the mandatory retirement age in Greece was only 58 years old with 80 percent of that sector getting pension payments. Workers then were even agitating for a lower retirement age. They did not succeed, of course, as Greece plunged in deeper debt, and in the pension reforms in 2010, the mandatory retirement was raised to 61, then 65.

A Filipino friend went to Greece a few years ago and stayed for four months. He observed that people had time to rally almost daily, demanding higher salaries but lesser work hours. Their lunch break was from 12 noon until 3-4 pm.

Last Sunday, July 5, the Greek majority voted NO to austerity measures that their country’s leaders earlier agreed upon with creditors. That vote may find resonance in that country’s being the birthplace of democracy. But the Tsipras government and its supporters effectively do not want to pay many of their huge debts, money that were used mainly to pay for the salaries and perks of government personnel and finance various welfare and pension subsidies.

THE PHILIPPINES AND SOUTHEAST ASIAN DEBT

Unlike in the critical 1980s, the Philippines today is much like its neighbors in the ASEAN. They are nowhere near the situation of Greece or the SPICy countries. The level of public indebtedness in ASEAN is just one-half or even one-fourth of those in the SPICy-G. The Philippines and Indonesia, in particular, have relatively low debt/GDP ratio. The denominator, the GDP, is rising faster than the numerator and, hence, the ratio for the Philippines is consistently declining. (See Figure 2)


LESSONS FROM THE GREEK FISCAL CRISIS

1. SHORT WORK: Early retirement with pension may be cool but it will punch a big hole in the annual budget, as the number of workers decreases while the number of pensioners increases, requiring additional public borrowings.

2. RULE OF LAW: If you borrow money, pay it. The bigger the debt, the stricter will be the conditions set by creditors. Follow those conditions whenever possible, do not blackmail creditors with emotional cries of “unjust, cruel conditions,” then demand that the terms be changed midway.

3. HUMILITY: If you cannot pay your debt on schedule, humbly ask for reconsideration and debt restructuring. It was you who begged for those loans in the past, not the creditors.

4. SAVINGS: If you can live beyond your means resulting in overspending and borrowings, learn also to live below your means on other years, cut spending and aim to have fiscal surplus and pay back some of those loans.

5. PRIVATIZATION: Other than more taxation and fees, substantial revenues can be realized through privatization of state-owned corporations and banks, wide land holdings, and other assets.

6. ROLE OF GOVERNMENT: Limit it to setting fair rules for all players and become an impartial referee in disputes, enforce the rule of law. Governments should refrain from being businessman-trader and business regulator at the same time. B. Oplas, Jr.


Bienvenido S. Oplas, Jr. heads Minimal Government Thinkers, a free-market think tank in Manila, and is also a fellow of the Kuala Lumpur-based South East Asia Network for Development (SEANET), which advocates economic freedom in the region.
-----------

See also: